I Geo-Economics & Chokepoints·Analysis·Middle East and North Africa
Two straits, one lever: why the Red Sea route is no longer a safe harbour while Hormuz is closed
The closure of the East-West pipeline and the Houthi seizure of the Bab el-Mandeb coast put both exit routes for Gulf exports under pressure in the same week.
Energy & Shipping Desk · 16 September 2026 · 9 min read · 7 sources
Why it matters
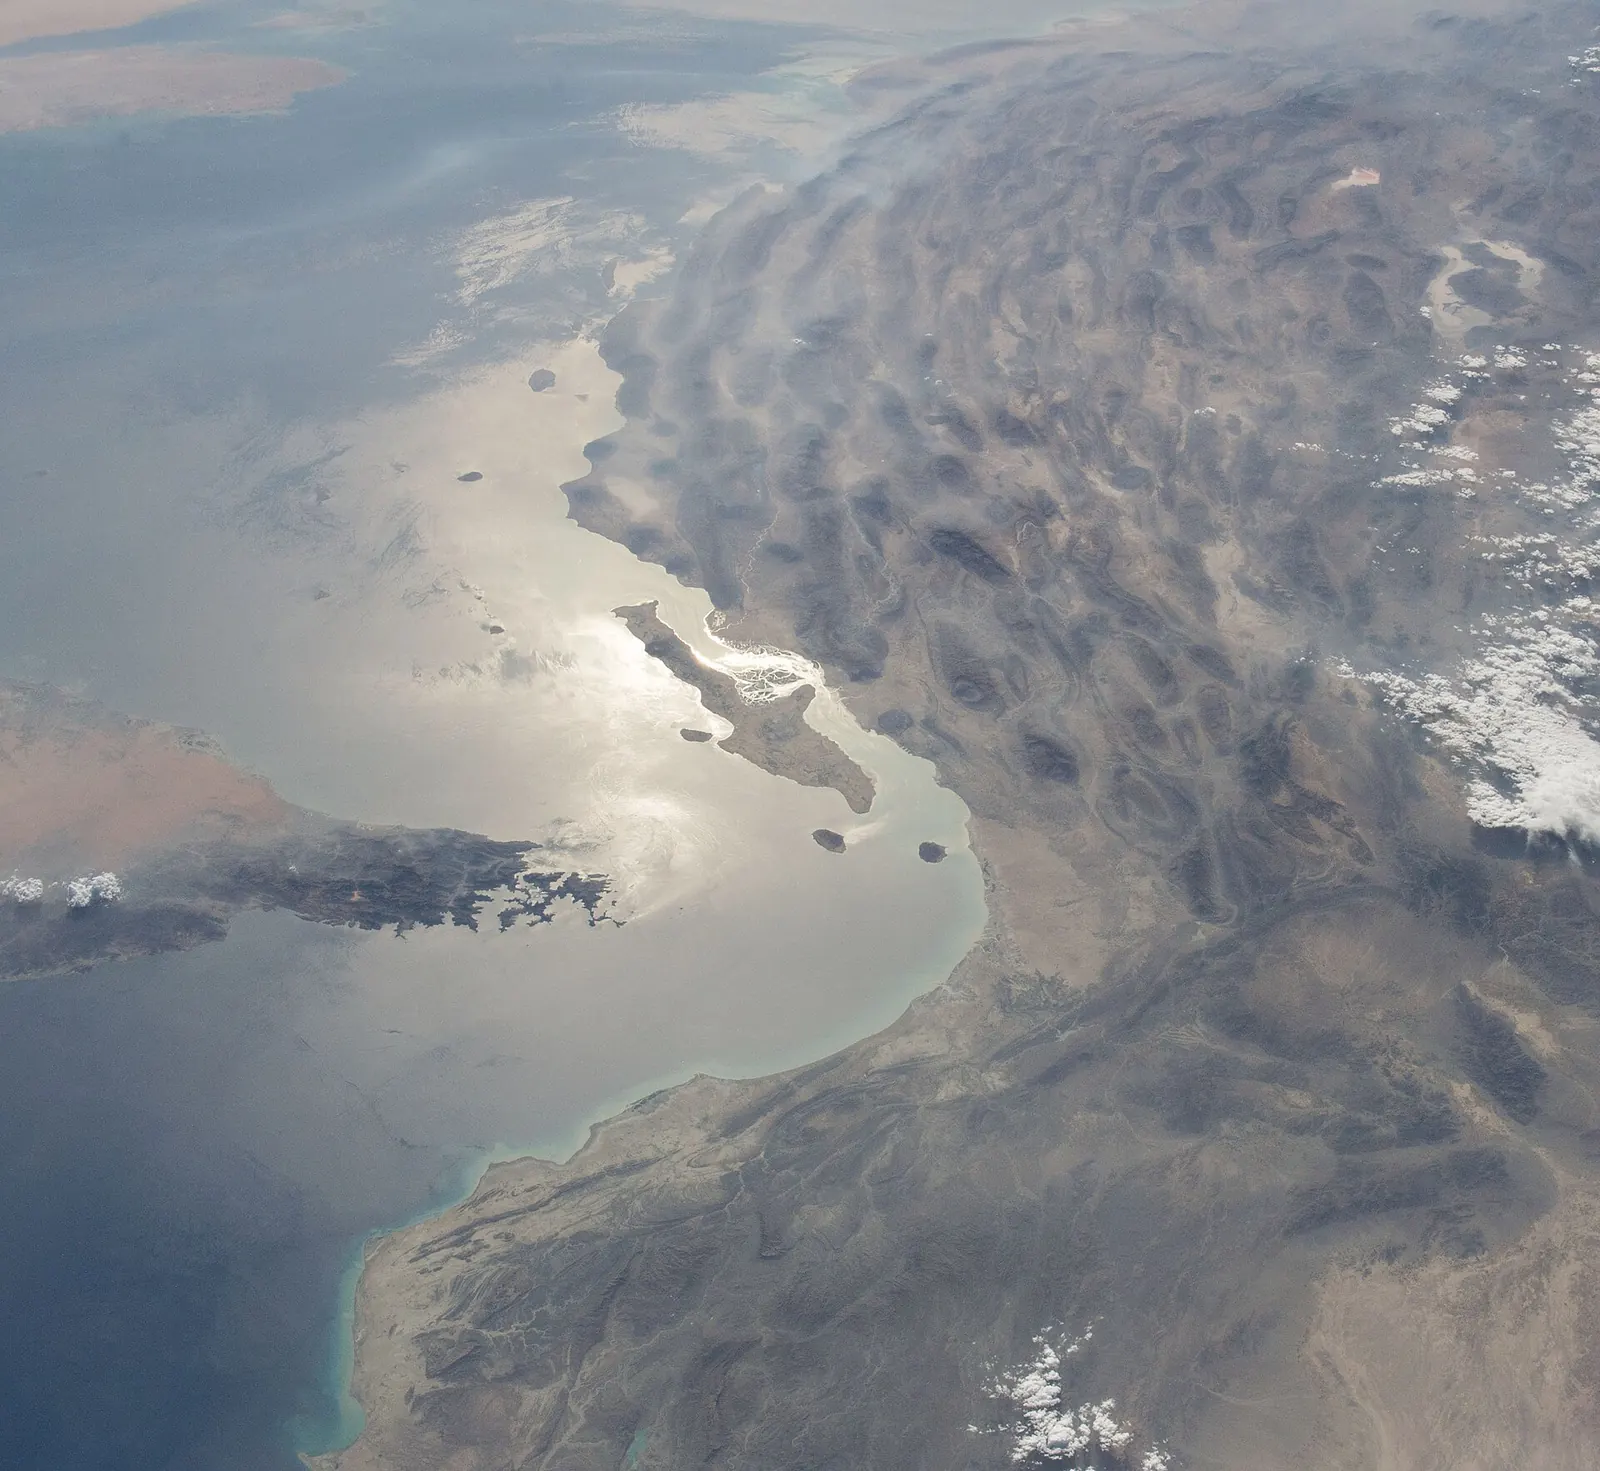
Since the Strait of Hormuz closed, the main alternative for Gulf oil has been the Saudi East-West pipeline and the Red Sea. On 10–11 September both links of that alternative were hit. There is no shock absorber left in the system: according to the IEA, OPEC+ effective spare capacity stands at 0.22 million barrels a day.
Implications
- While Brent futures rose to 109 dollars on 15 September, the physical spot price on FRED exceeded 130 dollars; the gap between futures and spot is a measure of physical tightness.
- A persistent risk premium grounded in territorial control is forming on the Red Sea route; freight and war risk insurance costs are rising structurally rather than falling.
- Current account and inflation pressures are building in energy-importing economies; in Türkiye, diesel prices were raised by about 6.6 lira on 15 September.
How the buffer ran out
When the Hormuz crisis began, there were three reasons the market stayed calm: Saudi Arabia's ability to move oil via the East-West pipeline to the port of Yanbu on the Red Sea, stock draws and US exports. According to the IEA's report of 11 September, 507 million barrels have been drawn from global stocks since February; in August alone the draw was 95 million barrels. The same report says OPEC+ produced about 7.27 million barrels a day below its targets in August, and effective spare capacity fell to 0.22 million barrels a day.
This picture shows that the price level is misleading. Brent holding at three-digit levels does not mean the shock has been absorbed; it means the system is staying afloat by spending its buffers. Ken Koyama of the Institute of Energy Economics, Japan draws attention to the same point in his piece of 4 September: stock draws have markedly lowered global inventory levels and reduced flexibility against new shocks.
Both links of the alternative route were hit in the same week
As reported by Al Jazeera and ABC, drones launched from Iraq struck the East-West pipeline and the line was shut as a precaution. The pipeline is reported to carry 4–5 million barrels of oil a day. While the Saudi Energy Minister said the line would reopen within days, sources quoted in the press say repairs could take 5–6 weeks. This uncertainty alone is large enough to set the direction of prices.
In the same days, on 10 September according to PBS and Polis Analysis, the Houthis seized the port of Mocha on Yemen's Red Sea coast and the islands of Perim and Hanish in Bab el-Mandeb. According to figures cited by Khalid Al-Jaber of the Doha-based Middle East Council on Global Affairs, oil passing through Hormuz fell from 20.9 million barrels a day in the first half of 2025 to 4.9 million barrels a day in the second quarter of 2026, while flows through Bab el-Mandeb rose from 4.2 million to 8.1 million barrels a day. In other words, the Houthis now stand at the gate of a far larger volume than before. These quarterly figures are as reported by the author and could not be independently verified.
Why the data and the official narrative do not match
US Energy Secretary Chris Wright said on 13 September that an average of 10 million barrels a day had passed through Hormuz over the past week. In the same days, Reuters tracking data showed a total of 14 ships, while straits.live, based on PortWatch data, showed 8 transits for 13 September. The normal pre-war number of daily transits ranges between 85 and 138 depending on the source. Convoys under military escort not appearing in commercial tracking systems may explain part of the gap, but there are no data confirming this.
Price behaviour supports the low-flow scenario. While the Brent futures contract was around 109 dollars on 15 September, FRED's physical spot series exceeded 130 dollars. This spread between the futures price and oil for immediate delivery shows that the market regards the disruption as temporary, but that finding physical oil today is very expensive. Because the two measures capture different things, both should be reported.
What to watch
In the near term three indicators are decisive: the reopening date of the East-West pipeline, whether the temporary Iran–Oman corridor is implemented at the postponed Salalah meeting, and how transit numbers in Bab el-Mandeb change after Houthi control. According to Lloyd's List Intelligence, 290 ships transited Suez in the week of 24–30 August, 36 per cent below normal. September data could not yet be verified.
The structural question is this: an attack risk can be calmed through bargaining, but territorial control is not easily reversed. The Red Sea route has therefore ceased to be a backup for Hormuz and has become a second breaking point within range of the same adversary. This lengthens the time it takes for reopening headlines to translate into physical supply.
Probabilities
Scenarios
| Scenario | Probability | Trigger | Market impact |
|---|---|---|---|
| H1Protracted siege | 55% | The pipeline stays shut for weeks and the Salalah corridor is not implemented. | Physical tightness persists and the spread between spot and futures stays wide. |
| H2Partial reopening | 25% | The pipeline reopens within days and the Iran–Oman corridor operates in a limited way. | Transit numbers rise and the spot price falls quickly towards futures. |
| H3Second rupture | 20% | Territorial control in Bab el-Mandeb feeds through to trade, or Saudi export infrastructure is attacked again. | With no buffer, the disruption passes straight through to prices. |
Module A
Constraints Matrix
STRUCTURAL AVG 4.7 · TACTICAL AVG 3.3Structural constraints dominate: the outcome is set more by these limits than by the actors' preferences.
Hard structural constraintspersistent · beyond the actors' will
Geographic chokepoint · Iran
5/5Both exit routes for Gulf exports lie within range of the same adversary; alternative pipeline capacity is limited.
Spare capacity exhausted · Saudi Arabia
5/5According to the IEA, OPEC+ effective spare capacity is 0.22 million barrels a day; there is no output to cover a new disruption.
Erosion of the stock buffer
4/5507 million barrels have been drawn from global stocks since February; the system's capacity to absorb shocks has shrunk.
Tactical frictiontemporary · eases over time
Pipeline repair time weeks
4/5The official statement says days, press sources say 5–6 weeks; the uncertainty is setting the direction of prices.
Diplomatic calendar days
3/5The Salalah meeting was postponed at Saudi request; the corridor is conditional on lifting the blockade.
War risk insurance weeks
3/5After the tanker attacks and the El Gaia incident the threat level is at its highest; voyage costs are rising.
Module B
Signal vs Noise
SIGNAL 60% · NOISE 40%
- SIGNAL
Spare capacity has fallen to 0.22 million barrels a day
IEA September report: OPEC+ produced about 7.27 million barrels a day below target in August; there is no buffer to cover a new disruption.
Data: Brent crude oil ›IEA — Oil Market Report, September 2026
- SIGNAL
Attack risk on the Red Sea route has turned into territorial control
On 10 September the Houthis seized Mocha and the islands of Perim and Hanish; the strait's southern gate is under the control of an armed group.
- SIGNAL
Spot price more than 20 dollars above futures
FRED Brent spot series at 130.80 dollars on 15 September; the futures contract around 109 dollars the same day. Physical oil is very expensive today.
- NOISE
OPEC+ quota decisions
OPEC left October output unchanged on 6 September; with production far below target, a quota change does not alter physical supply.
- NOISE
Headlines that Hormuz is reopening
Iran makes the corridor conditional on lifting the blockade and the Salalah meeting was postponed; tracking data show 8–14 ships a day.
Data: Strait of Hormuz transits ›Al Jazeera — Temporary Hormuz solution deferred
Module C
Asset-Class and Positioning Implications
| Asset class | Exposure | Transmission channel | H1 | H2 | H3 | Expected | Conviction | Horizon | What to watch |
|---|---|---|---|---|---|---|---|---|---|
| Commodities | Crude oil futures curve | Physical supply disruption and erosion of the stock buffer | ++ | −− | ++ | +1.00 | ●●● | 0–3 months | The spread between spot and futures |
| Freight & insurance | Tanker freight and war risk premium | Longer routes and territorial control in the Red Sea | ++ | − | ++ | +1.25 | ●●● | 0–3 months | Suez and Bab el-Mandeb transit numbers |
| FX | Energy-importing emerging market currencies | Current account via the energy bill | − | + | −− | −0.70 | ●●● | 3–12 months | Brent spot price and current account data |
| Sovereign debt | Gulf exporter sovereign credit risk | Attacks on export infrastructure | − | + | −− | −0.70 | ●●● | 3–12 months | Reopening date of the East-West pipeline |
Triggers
Thresholds to watch
| Indicator | Threshold | Today | What it means |
|---|---|---|---|
| Brent crude oil | > 120 | 130.80 | Futures tracking spot: the zone where the temporary-disruption assumption ends. |
| Strait of Hormuz transits | > 40 ships/day | 14 | First physical evidence that the corridor is actually working. |
| Suez Canal transits | < 35 ships/day | 21 | Territorial control on the Red Sea route feeding through to trade. |
Sources
- IEA — Oil Market Report, September 2026
- Al Jazeera — Saudi Arabia shuts critical oil pipeline
- PBS NewsHour — Houthis seize an island in a key strait
- Middle East Council on Global Affairs — The Gulf caught between Hormuz and Bab al-Mandab
- Al Jazeera — US says it is clearing Hormuz traffic
- Lloyd's List Intelligence — Red Sea brief, 3 September 2026
- FRED — Europe Brent spot price
Sourcing and verification rules: methodology · Report an error: contact
Related reports
IGeo-Economics·Analysis·Sub-Saharan Africa
Africa's fuel problem is no longer price but the last mile: the valve, the road and the pump are cut separately
Brent fell from 104.82 dollars on 17 September to 100.05 dollars on 22 September. In the same five days a valve in Libya, a trunk road in Mali and petrol stations in Sudan were cut off; the cheaper barrel touched none of them.
Africa Desk · 22 September 2026 · 9 min
IGeo-Economics·Analysis·Eurasia
Russia's refining loss has stopped being a war statistic and become a monetary policy line: 45% of capacity is out
Both distillation units at the Moscow Refinery burned, and the Kuibyshev and Ufaneftekhim plants were struck on the night of 21–22 September. The Bank of Russia now counts fuel prices within the core inflation dynamic in its rate statement.
Eurasia Desk · 22 September 2026 · 9 min
IGeo-Economics·Analysis·Europe
The buffer is thin in two places at once: European storage at 68.5% while the Asian spot climbs to 30 dollars
Europe enters winter with storage 68.5% full while Asian spot LNG has climbed to 30 dollars. Two sides are competing for the same cargoes, and the outcome is measured not by price but by who withdraws from the market.
Energy & Shipping Desk · 18 September 2026 · 9 min