I Geo-Economics & Chokepoints·Analysis·Europe
The buffer is thin in two places at once: European storage at 68.5% while the Asian spot climbs to 30 dollars
Europe enters winter with storage 68.5% full while Asian spot LNG has climbed to 30 dollars. Two sides are competing for the same cargoes, and the outcome is measured not by price but by who withdraws from the market.
Energy & Shipping Desk · 18 September 2026 · 9 min read · 9 sources
Why it matters
The only fast way to close Europe's storage gap is spot LNG; but there is a queue of buyers for the same cargoes in Asia. When Asian spot LNG rose from a floor of about 10 dollars to 30 dollars/mmBtu, Bangladesh and Pakistan were priced out: 78% of Bangladeshi knitwear factories partly halted production. The buffer is thin in two places at the same time — in Europe's storage and in South Asia's ability to pay.
Implications
- European storage, at 68.5%, is roughly 16 points below the seasonal average; the TTF front-month contract for 17 September was reported at two different levels in two sources, 76.98 and 78.60 euros/MWh.
- When Asian spot LNG rose from a pre-conflict floor of about 10 dollars to 30 dollars/mmBtu, 78% of factories in Bangladesh partly halted production; the measure of competition is no longer price but who withdraws from the market.
- In the same week Russian gas to Armenia was cut between 15 and 25 September (82% of imports came from Russia in 2025) and in Libya the PFG halted three facilities and issued an ultimatum over seven fields: simultaneous squeezes on the edge lines.
The storage gap: a volume problem, a price symptom
As Europe closes the injection season it finds its underground storage 68.5% full; according to TradingPedia's report of 17 September 2026 that level is roughly 16 points below the seasonal average. On the same day two sources diverge on where the TTF front-month contract traded: TradingEconomics reports 78.60 euros/MWh and a daily rise of 0.73%, while TradingPedia reports a fall of 1.23% to about 76.98 euros/MWh and a one-week low. The 1.62 euro difference between them may stem from the intraday trading hour; it could not be independently verified and has been recorded here as a contradiction.
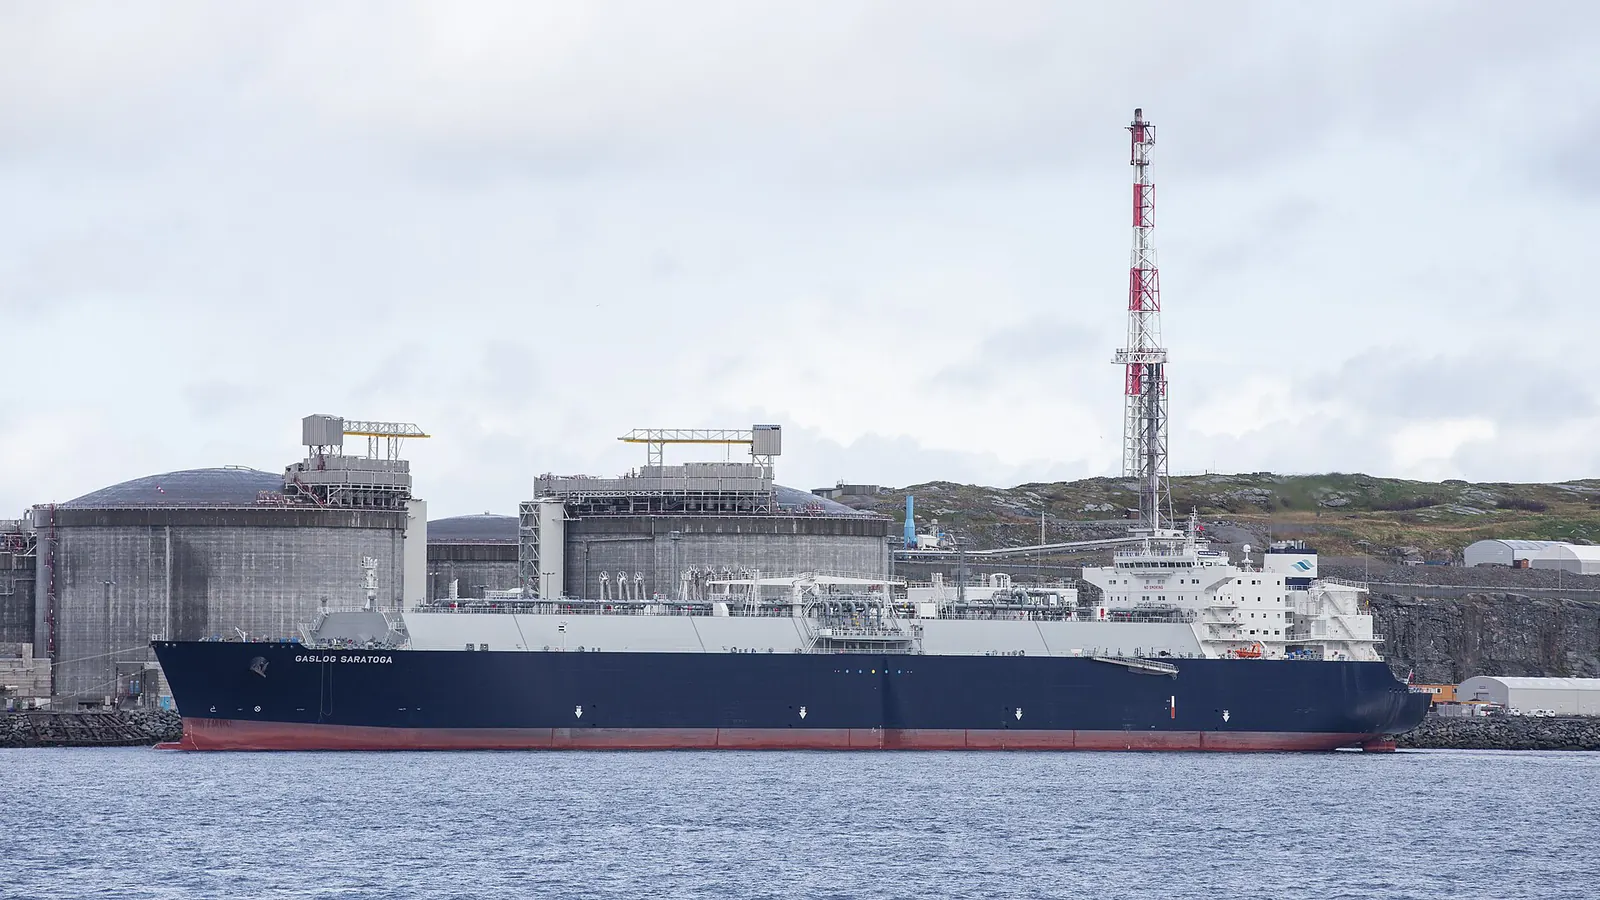
This one-day fall in the price is not a structural easing. What produced it was the end of a 24-hour strike at Dunkirk, France's largest LNG import terminal, which had cut daily capacity from at least 9.4 GWh to 4 GWh: the one-day return of a single terminal. The source of the gap, meanwhile, remains in place; with the Strait of Hormuz largely closed to commercial shipping, Qatari LNG exports are constrained, and planned maintenance at Norwegian facilities is reducing pipeline supply. Fullness is a measure of stock, while TTF is the cost of replenishing that stock: a stock 16 points below the seasonal average means fewer days of buffer going into winter, wherever the price stands.
The same cargo, two buyers: the measure of competition is not price
The only quick way to close Europe's storage gap is spot LNG. But there is a queue of demand for the same cargoes in Asia, and that queue is culled not by price but by ability to pay. The Asian spot LNG price rose this week from a pre-conflict floor of about 10 dollars/mmBtu to roughly 30 dollars/mmBtu; it was the year's second price jump. On Shell's estimate, some 36 million tonnes of LNG supply from the Middle East was lost in 2026. That lost volume forces Europe and South Asia to draw from the same pool.
The outcome has to be read not in the price curve but in industrial output. Bangladesh, which generates more than 40% of its electricity from imported LNG and used to source 95% of those imports from Qatar, has in effect been out of the market at a spot level of 30 dollars. According to BKMEA's survey of the knitwear industry, 78% of factories have partly halted production and 55% reported that buyers had cancelled or cut orders since the end of August. At one factory an order of 50,000 pieces was reduced to 40,000, and meeting the delivery date produced an air freight cost of 50,000 dollars on a single shipment. Bangladesh's energy ministry confirmed that industrial output was slowing.
On the Pakistani side the picture is tighter still. Against a power sector gas requirement running to 400 million cubic feet a day through the winter, only two LNG cargoes were confirmed for September; a standard cargo is about 140,000 cubic metres, that is 3 billion cubic feet, and corresponds to roughly a week of supply. When petrol reached 391 rupees (1.41 dollars) and diesel 421 rupees (1.52 dollars), the government turned to a subsidy of 100 rupees a litre and to closing bazaars at 21.00. These are not a price response but instruments of rationing.
This picture may look like good news for Europe: as a rival withdraws, cargoes become easier to find. But that is not how a buffer is measured. The withdrawal of Bangladesh and Pakistan shows not that supply has increased but that price has begun to ration supply. Once rationing has started, the cost of closing Europe's gap no longer rests on the most elastic part of the demand curve but on the most rigid part: its own storage and its own winter.
Simultaneous squeezes on the edge lines
Within the same week two more supply nodes locked up, and both teach the same lesson: dependence on a single line turns into fragility even in a planned operation. Gazprom halted gas flows to Armenia from 15 September to 25 September because of planned maintenance on the North Caucasus-Transcaucasus pipeline. In 2025 Russia supplied Armenia with 2.7 billion cubic metres of gas; that is 82% of the country's gas imports, at a price of 177.5 dollars per 1,000 cubic metres. The gap is to be covered from domestic reserves and from Iranian imports whose volume has not been disclosed. The sources diverge on the length of the cut: the Moscow Times takes the 15-25 September window while OC Media reports a ten-day interruption. The current agreement ends at the close of 2026 and the renewal terms have not been announced.
In Libya the interruption is on the oil rather than the gas side, but the mechanism is the same. On 15 September the Petroleum Facilities Guard closed a valve on the Hamada-Zawiya line, halting the Hamada and Tahara fields and the NC5 station; it threatened to shut seven fields, including Sharara and El Feel, if its demands were not met within a week. The NOC deemed the closure unlawful and warned that it might declare force majeure, but had not done so as of 15 September, and published no estimate of the output lost. In a country where oil makes up about 90% of the economy, the fact that a single group can close a valve shows that the supply risk is institutional rather than technical. Gas and oil are separate markets, but they are written into the same winter budget.
Where Türkiye stands in this equation
Türkiye is tied to both channels at once: an importer that relies on long-term pipeline gas contracts and on spot LNG alike. TTF is one of the main references for Türkiye's spot purchase cost; the price staying in the 77-79 euro band keeps the import bill and the energy pressure on the current account high. But unlike Bangladesh and Pakistan, Türkiye is not a buyer priced out at a spot level of 30 dollars; it stands on the expensive side of the competition rather than the losing side. The distinction matters: the loss here is measured not as a halted factory but as a bill. Because the source event records contain no direct volume or bill data for Türkiye, this link is drawn at the level of mechanism, without figures.
The second-round effects are on the trade and corridor side. With production partly halted at 78% of factories in Bangladesh's knitwear industry and an air freight cost of 50,000 dollars arising on a single shipment, delivery time risk moves ahead of price risk for buyers; suppliers with the advantage of proximity gain in relative terms under such conditions. Armenia seeing the cost of taking 82% of its imports through a single line, meanwhile, turns the debate about alternative corridors in the region into a political heading. The cutting of oil revenue in Libya additionally pushes back the collection timetable for contracting receivables tied to public payments.
What to watch
Three indicators will determine how the winter goes. First, the difference between EU storage fullness and the seasonal average: whether the gap, currently about 16 points, narrows or widens during the withdrawal season is a truer measure of the buffer than price. Second, whether the Asian spot LNG price stays around 30 dollars and whether the number of cargoes Pakistan confirms for October to December rises above September's two. Third, whether Qatari LNG flows through Hormuz recover: unless flows normalise, the loss Shell estimates at 36 million tonnes is not replaced.
The structural question is this: a storage gap can close within a few weeks if supply normalises. But in a market where price is culling buyers, normalisation can come not from supply rising but from demand disappearing for good. That orders have already been cancelled or cut at 55% of Bangladeshi factories is the first sign of it. On the day a fall in the gas price is measured, it is possible that the loss has already been written into another ledger. That is the real cost of the buffer being thin in two places at once: the price does not say which side has been repaired.
Probabilities
Scenarios
| Scenario | Probability | Trigger | Market impact |
|---|---|---|---|
| H1A two-way squeeze persists | 50% | The Hormuz constraint and the narrowing in Qatari LNG flows persist; the EU storage gap stays in the 16-point band. | Europe keeps competing with Asia for cargoes; price rationing becomes permanent in South Asia. |
| H2Supply partly normalises | 25% | Norwegian maintenance ends, Qatari flows through Hormuz partly reopen and spot LNG falls towards the 10 dollar floor. | Storage injection accelerates and South Asia becomes able to take cargoes again. |
| H3A cold snap and a second interruption | 25% | An early cold snap accelerates storage withdrawal while seven fields close in Libya or an Armenia-type interruption is repeated. | With no buffer left, the interruption passes straight into price; Europe and Asia collide directly over the same cargoes. |
Module A
Constraints Matrix
STRUCTURAL AVG 4.5 · TACTICAL AVG 3.3Structural constraints dominate: the outcome is set more by these limits than by the actors' preferences.
Hard structural constraintspersistent · beyond the actors' will
The size of the storage gap · European Union
5/5EU storage, at 68.5%, is roughly 16 points below the seasonal average; with the injection season closing, this gap cannot be closed during the winter.
The volume of LNG lost
5/5On Shell's estimate, some 36 million tonnes of LNG supply from the Middle East was lost in 2026; there is no near-term substitute for that volume.
The closure of Hormuz · Iran
4/5The strait remaining largely closed to commercial shipping constrains Qatari LNG exports; Europe and Asia draw from the same narrowed pool.
Single-line dependence · Russia
4/5Armenia takes 82% of its gas imports through a single Russian line; in 2025 that came to 2.7 billion cubic metres, and even planned maintenance halted supply.
Tactical frictiontemporary · eases over time
Institutional dispute in Libya weeks
4/5Until it is settled which body the PFG answers to, the valve lever stays in its hands; the NOC announced that it might declare force majeure but has not yet done so.
Volatility of terminal capacity days
3/5A 24-hour strike at Dunkirk cut daily capacity from at least 9.4 GWh to 4 GWh; a single day at one terminal moves the price measurably.
Norwegian planned maintenance weeks
3/5Planned maintenance at Norwegian facilities is temporarily reducing pipeline supply to Europe and slowing the pace at which the storage gap closes.
The Armenian contract timetable months
3/5The current bilateral gas agreement ends at the close of 2026; because renewal terms have not been announced, an interruption can turn from technical maintenance into a bargaining matter.
Module B
Signal vs Noise
SIGNAL 60% · NOISE 40%
- SIGNAL
The storage gap is roughly 16 points below the seasonal average
EU underground storage was 68.5% full as the injection season closed; that level is presented as among the lowest of the past twenty years.
Data: EU gas storage fill level ›TradingPedia — European gas and the storage level
- SIGNAL
Price is now culling buyers rather than trimming demand
Asian spot LNG rose from a floor of about 10 dollars to 30 dollars/mmBtu; 78% of Bangladeshi knitwear factories partly halted production and 55% saw orders cancelled or cut.
- SIGNAL
Pakistan's September supply buffer was limited to two cargoes
Against a power sector gas requirement running to 400 million cubic feet a day through the winter, two cargoes were confirmed for September; one cargo is about 3 billion cubic feet, roughly a week of supply.
The Business Standard — Energy disruption in Bangladesh and Pakistan
- NOISE
TTF's daily fall on 17 September
The front-month contract fell 1.23% to about 76.98 euros/MWh, but the cause was the end of the 24-hour strike at Dunkirk; the storage gap stayed at 68.5% the same day.
Data: EU gas storage fill level ›TradingPedia — European gas eases as French LNG capacity returns
- NOISE
The statement that output in Libya has returned to normal
The NOC published no estimate of output lost, exports blocked or the revenue shortfall; the statement that output has returned to normal could not be confirmed with figures, and the Hamada and Tahara fields were reported closed.
Data: Brent crude oil ›Energynews.pro — Libya halts three oil facilities
Module C
Asset-Class and Positioning Implications
| Asset class | Exposure | Transmission channel | H1 | H2 | H3 | Expected | Conviction | Horizon | What to watch |
|---|---|---|---|---|---|---|---|---|---|
| Commodities | European gas benchmark price | Pass-through of the storage gap to price through competition for spot LNG | ++ | −− | ++ | +1.00 | ●●● | 0–3 months | The difference between storage fullness and the seasonal average |
| Commodities | Crude oil supply risk premium | The possibility of seven fields closing in Libya and the risk of force majeure | + | − | ++ | +0.75 | ●●● | 0–3 months | Whether the NOC declares force majeure |
| Freight & insurance | LNG shipping and routing costs | Cargoes being redirected between Asia and Europe and the lengthening of distances | + | − | ++ | +0.75 | ●●● | 0–3 months | The gap between Asian spot LNG and the European benchmark price |
| FX | Currencies of energy-importing emerging economies | Pressure of the energy bill on the current account and on inflation | − | + | −− | −0.75 | ●●● | 3–12 months | Spot LNG prices and monthly energy import bill data |
| Credit | Credit risk in LNG-dependent South Asia | Balance of payments pressure and the fiscal cost of fuel subsidies | −− | + | −− | −1.25 | ●●● | 3–12 months | Pakistan's number of confirmed cargoes and the subsidy burden |
| Equities | Energy-intensive European industrial sectors | Input costs staying in a high band and the risk of output cuts | − | + | −− | −0.75 | ●●● | 3–12 months | The European gas benchmark band and industrial production data |
Triggers
Thresholds to watch
| Indicator | Threshold | Today | What it means |
|---|---|---|---|
| EU gas storage fill level | < 65 | 68.0 | Below 65% as the withdrawal season begins: the zone where Europe sustains the competition for cargoes out of necessity rather than choice. |
| Strait of Hormuz transits | < 30 ships/day | 14 | Physical confirmation that Qatari LNG flows have not normalised; it means the supply loss of 36 million tonnes is not being replaced. |
| Brent crude oil | > 120 | 130.80 | The zone where Libyan supply risk is added to the gas bill through a second channel and the current account of importers hardens. |
Sources
- TradingEconomics — EU natural gas price and market note
- TradingPedia — European gas eases as French LNG capacity returns
- Dawn — Energy disruption hits Pakistan and Bangladesh as Gulf crisis worsens
- The Business Standard — Energy disruption hits Bangladesh and Pakistan as Gulf crisis worsens
- The Moscow Times — Russia suspends natural gas exports to Armenia for repair work
- OC Media — Daily briefing, 16 September 2026
- The Media Line — Libya oil security force shuts 2 fields, threatens full production halt
- Libya Herald — PFG threatens complete closure of seven oil fields including Sharara and El Feel
- Energynews.pro — Libya halts three oil facilities amid wage dispute
Sourcing and verification rules: methodology · Report an error: contact
Related reports
IGeo-Economics·Analysis·Sub-Saharan Africa
Africa's fuel problem is no longer price but the last mile: the valve, the road and the pump are cut separately
Brent fell from 104.82 dollars on 17 September to 100.05 dollars on 22 September. In the same five days a valve in Libya, a trunk road in Mali and petrol stations in Sudan were cut off; the cheaper barrel touched none of them.
Africa Desk · 22 September 2026 · 9 min
IGeo-Economics·Analysis·Eurasia
Russia's refining loss has stopped being a war statistic and become a monetary policy line: 45% of capacity is out
Both distillation units at the Moscow Refinery burned, and the Kuibyshev and Ufaneftekhim plants were struck on the night of 21–22 September. The Bank of Russia now counts fuel prices within the core inflation dynamic in its rate statement.
Eurasia Desk · 22 September 2026 · 9 min
IGeo-Economics·In-depth analysis·Türkiye and Its Neighbourhood
From a struck distillation unit to 100-lira diesel: Russian refinery capacity and Türkiye's three-channel bill
Ukrainian drones are cutting Russian refinery capacity, Moscow is closing exports and Türkiye is losing half its cargo allocation. But the 100 lira at the pump is the sum not of one shock but of three separate channels.
Türkiye & Neighbourhood Desk · 18 September 2026 · 12 min